
Money Clarity

    Subscription tracker in India: four places charges hide

    The subscription that costs you most is rarely the one you forgot you had. It is the annual plan that renewed once, quietly, at ₹6,199 instead of last year's ₹4,899, and the free trial that became ₹349 a month while you were busy with something else. A monthly scroll through your UPI app catches neither. That is the real test of a subscription tracker in India: not how neat its list looks, but whether it looks where these charges actually sit.

    They sit in four places that never share a screen. UPI AutoPay mandates live inside whichever payment app created them. Card standing instructions live with the card issuer. App-store billing lives with Google Play. Annual renewals live on whichever of those paid for them, and surface in one statement out of twelve. People who say they have checked their subscriptions have usually checked one of the four.

    Below: where each place is visible and where it is not, one household's twelve subscriptions priced across all four, the two traps that cost the most, a 20-minute audit in order, a rule for deciding, and what a tracker must see to be worth having. The tapping-through of cancelling a mandate has its own page; this one is about finding what deserves cancelling.

    Last reviewed 2026-10-09

    Four places a subscription can live

    The technique

    Each rail keeps its own list

    People open the place where they remember signing up and treat it as the full list. A mandate created in one payment app does not appear in another, a card instruction never appears in any UPI app, and a Google Play charge reaches the card statement under the store's name rather than the app's.

    UPI AutoPay is the rail most people know about, because the app asks for your PIN when the mandate is set up. It is created inside GPay, PhonePe, Paytm or the merchant's own app, and it is listed only in the app that created it. If you have used three UPI apps over the years, you have three lists.

    Cards work under the RBI's e-mandate framework for recurring payments. You register a standing instruction with an extra authentication step, the issuer sends a notice before each charge, charges above a set limit need fresh approval, and you can withdraw the instruction. Useful protections, all of them, and none puts the list anywhere you look by habit. NACH mandates also debit your account on a schedule, but they mostly carry EMIs, premiums and SIPs rather than subscriptions.

    The fourth place is not a rail but a clock. An annual plan is charged through one of the other three, once, and then vanishes from view for eleven months.

    PlaceSet up inWhere it is visibleWhere it does not show
    UPI AutoPay mandateGPay, PhonePe, Paytm or the merchant's appThe mandate list in the app that created it; each debit on the bank statementAny other UPI app; the card statement
    Card standing instructionThe merchant's checkout, under the e-mandate rulesThe card statement; the pre-debit notice; the issuer's mandate page, where one existsEvery UPI app; the bank statement, which shows only the card bill total
    App-store billingInside an app, through Google PlayThe Play subscriptions list; a charge under the store's nameThe app's own name on any statement; another family member's account
    Annual renewalAny of the three, billed once a yearThe one statement in twelve that carries it; the renewal emailA monthly check in the other eleven months
    Typical behaviour; where each app places its mandate list changes with updates. The same service can be paid through a different place by different people in one household.
    • The bank statement is the only record that touches all four, and it names most of them badly: a mandate reference, a payment gateway, or the store instead of the service
    • Two adults in one house means two sets of all four places. A spouse's Play account billing the spouse's card appears nowhere you can see from your own phone

    Finding unused subscriptions in one household

    Take a couple with twelve subscriptions, none of them outrageous on its own. Nine bill monthly, three bill once a year. Here they are by place, priced per year so that monthly and annual items can be compared. The figures are illustrative; the method is to rebuild this table from your own statements.

    By place, the cards carry 36.3 percent of the spend, annual renewals 24.6 percent, UPI AutoPay 23.5 percent and Google Play 15.7 percent. The UPI mandate list, the one place most people check, holds under a quarter of the money.

    What the audit is worth in this household
    All twelve subscriptions, per year
    ₹36,633
    Same, as a monthly figure
    ₹3,053
    Six unused or duplicated items, per year
    ₹15,411
    Share of the total
    42.1%
    Premium video tier downgraded to ₹199
    ₹3,600
    Saved by cancelling and downgrading
    ₹19,011 (51.9%)
    Still paid, for things actually used
    ₹17,622

    Unused means no use in the last 60 days. Duplicates are the spouse's storage plan and the antivirus: ₹2,859 a year.

    SubscriptionPlaceBilledPer yearStatus
    Video streaming, family planUPI AutoPay₹299 a month₹3,588Used
    Second video streamingUPI AutoPay₹199 a month₹2,388Unused since the series ended
    Music streamingUPI AutoPay₹119 a month₹1,428Used daily
    News appUPI AutoPay₹99 a month₹1,188Unused
    Third video streaming, premium tierCard₹499 a month₹5,988Used on one phone
    Fitness appCard₹399 a month₹4,788Unused
    Cloud storage, 200 GBCard₹210 a month₹2,520Used
    Cloud storage, 100 GB (spouse)Google Play₹130 a month₹1,560Duplicate
    Photo editing app, converted trialGoogle Play₹349 a month₹4,188Unused
    Productivity suite, familyAnnual₹6,199 a year₹6,199Used
    AntivirusAnnual₹1,299 a year₹1,299Duplicate of phone's built-in
    Delivery membershipAnnual₹1,499 a year₹1,499Used
    Total₹36,633
    Illustrative household. Monthly items total ₹2,303 a month, ₹27,636 a year; annual items ₹8,997. No service is named because the pattern, not the brand, is the point.
    • Checking only the UPI mandate list finds two of the six items to cut, ₹3,576 a year, or 23.2 percent of the waste. The other ₹11,835 is on the card, in the Play store or on an annual clock
    • Duplicates are a household problem. Each person's own list looks clean; the waste only appears when both lists sit on one table

    The annual renewal and the converted trial

    The technique

    A monthly look misses the annual ones; an annual look misses the trials

    The two costliest failures run on different clocks. An annual renewal is absent from eleven statements out of twelve, so a monthly habit walks past it. A converted trial charges every month from the day it converts, so a once-a-year review finds it after a year of charges.

    Start with the renewal. The productivity suite cost ₹4,899 last year and renewed at ₹6,199: ₹1,300 more, a 26.5 percent rise. As a monthly figure that is ₹517 a month, ₹108 more than before. A ₹108 rise on a monthly bill would show on the next statement. On an annual plan it arrives as one charge, preceded by an email that says 'your plan will renew' and not always what it will cost.

    The delivery membership is the other version: a first-year introductory price of ₹899, renewing at the standard ₹1,499. That is ₹600 more, a 66.7 percent rise, and nobody raised any price; the discount simply ended. Between them, the two renewals went from ₹5,798 to ₹7,698, up ₹1,900 or 32.8 percent, and neither shows up in a monthly check.

    Now the trial. The photo editing app offered seven free days, took a small verification charge on the card, and converted to ₹349 a month. When it is found decides what it costs.

    One ₹349 trial conversion, found at different times
    Found at the first monthly look
    ₹349
    Found at a quarterly look
    ₹1,047
    Found after five charges, as in this household
    ₹1,745
    Found at a once-a-year review
    ₹4,188

    Assumes the app does not refund charges already taken, which is the common case. Some stores and apps refund a first charge on request; ask before assuming.

    • The defence against a renewal is a date, not a habit. Write down each annual item's renewal month and decide in the month before, when cancelling still saves the whole year
    • The defence against a trial is a reminder set the day you start it, two days before it ends. The store's own reminder, where there is one, arrives when you are least likely to act on it

    How to find my subscriptions in 20 minutes

    Do it in this order, because each step catches what the one before it cannot. You need your bank statements, your card statements, your phone and your spouse's phone.

    Minutes one to six: the bank statement. Download 13 months, not three. The extra ten catch every annual item, and the 13th catches one that renewed exactly a year ago. Search it for these terms one at a time: AUTOPAY, MANDATE, NACH, SI, ACH, RECURRING, RENEWAL, SUBSCRIPTION, PLAY. Descriptors differ by bank, so also scan for the same amount on the same date in consecutive months. Note each one and the date it first appeared.

    Minutes seven to eleven: every card statement, including add-on cards. Look for repeating amounts, charges in a foreign currency, which usually carry a markup on top, and one-rupee or two-rupee charges, which often mark the start of a trial.

    Minutes twelve to fifteen: Google Play, under the subscriptions list in your account, then the same on every other phone in the house.

    Minutes sixteen to twenty: the mandate list in every UPI app you have ever used, including ones you have not opened in a year. A mandate outlives the app's place on your home screen.

    • Write one line per item: name, place, amount, billing cycle, date of first charge and date of last real use. The last column decides everything in the next section
    • Once you know what to cut, cancel at the merchant first and then revoke the mandate. Where to tap in each app and bank is on the page on cancelling UPI AutoPay mandates

    Manage subscriptions: keep, downgrade or cancel

    The technique

    Would you sign up again today, at today's price?

    People decide on what they have already paid, which is gone either way. The only money the decision controls is the next charge, so the test prices that and ignores the rest.

    Keep it if you used it in the last 30 days and would sign up again at the current price. The music plan at ₹119 a month, used daily, passes easily.

    Downgrade it if you use it but a cheaper tier covers how you use it. The premium video tier at ₹499 was watched on one phone; the ₹199 tier covers that. The saving is ₹300 a month, ₹3,600 a year, with nothing given up.

    Cancel it if it has gone unused for 60 days, if someone else in the house already pays for the same thing, or if the only reason to keep it is the money already spent. The fitness app at ₹399 a month with no sessions fails all three ways of looking at it.

    For annual items, run the same rule a month early. Cancelling the day after a renewal usually saves nothing until next year, because most annual plans do not refund unused months.

    • Cost per use is the sharpest version: a ₹119 plan used 30 times costs about four rupees a use, a ₹399 plan used never costs ₹399 for nothing

    What a subscription tracker in India must see

    A tracker is useful only if it sees what the audit above finds by hand.

    All four places. A tool that reads one UPI app's mandate list sees 23.5 percent of this household's spend. One that reads the bank account sees card bills as totals and Play charges under the store's name.

    Annual items. It needs a year of history, or it cannot know a ₹6,199 charge is a renewal and not a one-off purchase.

    Price changes. It should compare each charge with the last one for the same merchant and say when they differ. That is what turns ₹4,899 into ₹6,199 from a surprise into a line on a list.

    New recurring merchants. The first charge after a free trial looks like any other purchase; the second, a month later, at the same amount, is the one to flag.

    Names, not handles. A UPI debit arrives with a handle and a mandate reference. Unless those are turned into a merchant name, the list is a list of codes.

    When a tracker will miss things

    Anything that never touches your accounts is invisible to every tracker, however good.

    Cash. A monthly class or a gym paid in cash is a withdrawal on the statement and nothing more.

    A family member's card. If a parent's card pays for a plan the whole family uses, or a spouse's Play account bills the spouse's card, it is on their statements, not yours.

    Gift subscriptions. Someone else paid for the first year, so nothing appears. When the gift ends, some services ask for a card and carry on; that first charge is a new subscription wearing an old name.

    Bundles. A plan included in a mobile recharge or a broadband bill has no debit of its own. Its cost is inside the bill, and cancelling it usually means changing the plan.

    And sometimes a tracker is simply unnecessary. If you have three monthly plans you use every week and no annual ones, a 20-minute look once a year does the job.

    • Once a year, sit down with whoever else pays for things in the house and put both lists side by side. It is the only way to catch the duplicates no single record can show

    How Unyfy helps find subscriptions still charging

    The audit on this page works because it reads the bank and card records that touch all four places, and the step that takes the time is gathering them. The app does that gathering continuously. It reads your bank and card transaction emails and, on Android, your bank's transactional SMS, with each UPI handle turned into a merchant name from a database of about 10,000 entries. On Pro, its Fixed Expenses screen keeps a Subscriptions list built from those records.

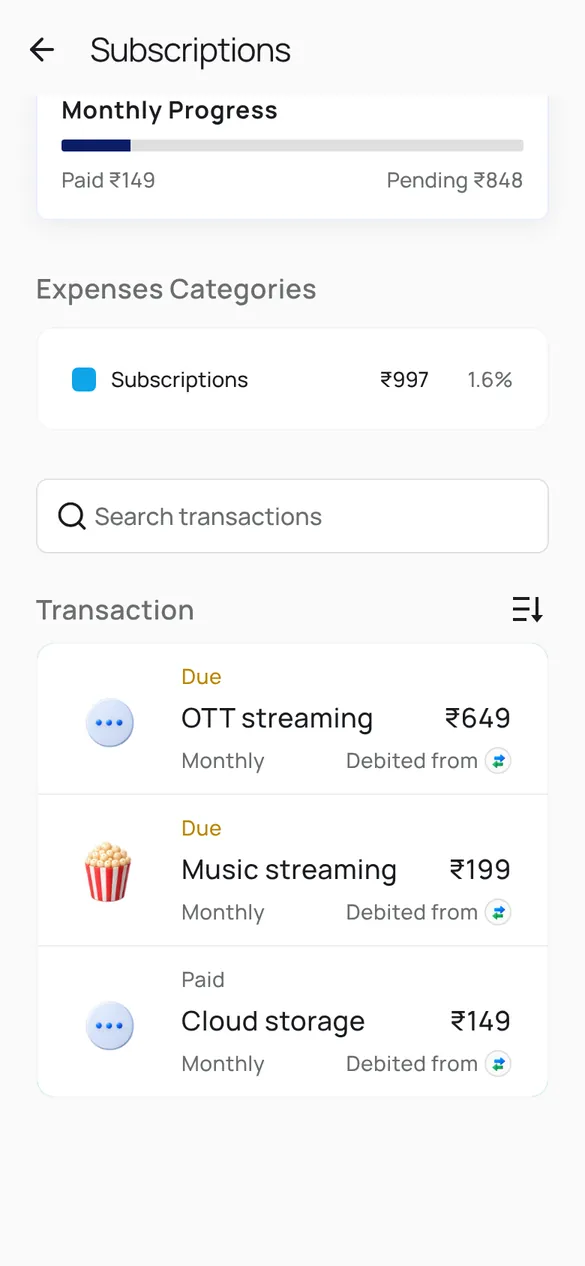
    What you see is close to the table the page builds by hand: one line per recurring subscription, with its amount and whether it is due or paid this month, and a detail for each showing how often it is paid, the usual payment days, how many past payments matched and the past months' payments. Setting each line against the keep, downgrade or cancel rule is yours, because only you know when you last used it.

    It never asks for your bank password or UPI PIN, and every payment is one you authorise. You cancel at the merchant, then revoke the mandate in the app that created it.

    Install Unyfy on Android, or use the web app at app.unyfy.co.in on an iPhone.

    Unyfy Subscriptions list inside Fixed Expenses showing streaming and storage subscriptions, each marked due or paid

    1.Subscriptions

    Each subscription with its amount and whether it is due or paid this month. On Pro.

    Screens from the Unyfy app with sample data for a sample user, not the example on this page. Subscriptions sit inside Fixed Expenses, a Pro feature.

    Common questions

    Is there a subscription tracker in India that finds everything?

    No single record shows every subscription. UPI AutoPay mandates are listed only in the app that created them, card standing instructions sit with the issuer, Google Play charges show under the store's name, and annual renewals appear once a year. A tracker that reads your bank and card records across a full year sees the most; cash, family members' cards and bundled plans stay invisible to all of them.

    How do I find unused subscriptions on my bank statement?

    Download 13 months, not three, so annual renewals are included. Search for AUTOPAY, MANDATE, NACH, SI, RECURRING, RENEWAL and PLAY, then scan for the same amount on the same date in consecutive months. Do the same on every card statement. Anything not used in the last 60 days is a candidate to cancel.

    How do I cancel subscriptions in India once I have found them?

    Cancel at the merchant first, so you keep access for the period already paid, then revoke the mandate so a retry cannot succeed. UPI AutoPay is revoked in the app that created it, a card instruction with the issuer, and a Google Play subscription in Play. The page on cancelling UPI AutoPay mandates has the steps for each app and bank. Unyfy's Subscriptions list, on Pro, shows each recurring subscription with its amount; you cancel at the merchant and in the app that set it up.

    Can a recurring payments tracker catch annual renewals?

    Only if it reads at least a year of history and compares each charge with the last one from the same merchant. Otherwise a ₹6,199 renewal looks like a one-off purchase. In the worked example a suite rose from ₹4,899 to ₹6,199, 26.5 percent, and a monthly check would have seen it in one month out of twelve.

    Why was I charged for a free trial I never used?

    Most trials take a card or UPI mandate at sign-up and convert automatically when the free days end. A ₹349 monthly conversion costs ₹349 if found at the first monthly look and ₹4,188 if found at a yearly review. Set a reminder two days before any trial ends, and look for one-rupee or two-rupee verification charges on your card: they often mark a trial start.

    A subscription tracker in India has to look in four places, over a full year, and notice when a price moves. In the worked household, twelve subscriptions cost ₹36,633 a year, ₹15,411 of it was unused or duplicated, and the UPI mandate list most people check held only ₹3,576 of that waste. The expensive items were a renewal that rose 26.5 percent and a trial that ran five months. Check monthly for trials, a month ahead for renewals, and both lists in the house once a year. Informational page, not financial advice. The household and prices are illustrative; billing, renewal and refund terms differ by service, and your statements and each provider's terms govern, not this page.

    Our Partners

    Banks and NBFCs we compare

    Unyfy compares offers from these lenders and earns a commission if you take one. The comparison is shown first, and it can tell you not to switch.

    HDFC Bank logo
    ICICI Bank logo
    Axis Bank
    State Bank of India logo
    IDFC First Bank logo
    Kotak Mahindra logo
    IndusInd Bank logo
    Yes Bank logo
    Bajaj Finserv logo
    Tata Capital logo






